November 9, 2026
Buying New Construction in North Scottsdale — What to Know
Buying new construction in Scottsdale starts with a base price, not the real one. See how upgrades, lot premiums, and incentives add up, and what to negotiate.
Buyer Guides · 15 Min Read
Buying New Construction in North Scottsdale — Builders, Timelines, and Negotiation
Buying new construction in Scottsdale starts with a base price and a model home, but the number you actually finance is built from options, a lot premium, and an incentive — and every one of those lines is written by the builder.
Key Takeaways
- North Scottsdale's active new-build supply sits mostly in 85255 and 85262 — Storyrock, Sereno Canyon, HighPoint, Shadow Ridge, The Edge at Joy Ranch, and Preserve Ranch — with most published ranges running from about $1.4M to above $4M and one entry point near $900,000.
- Builders are negotiating. As of 2026, the NAHB reports 43% of builders cutting prices, an average cut of 6%, and 65% using sales incentives. The question is which incentive, attached to which home, with which conditions.
- The all-in number is base plus options plus lot premium, minus the incentive — then add the landscaping and window coverings you will pay for in cash after closing.
- Bring your agent to the first visit. Arizona's Department of Real Estate notes that a buyer who registers alone may return with an agent, but that agent may not be paid by the builder.
- If you are selling a current home to fund the purchase, our listing fee is 1% with a $5,500 minimum. At $550,000 that is $5,500 rather than $16,500 at 3% — $11,000 more toward your down payment. No upfront costs. Brokered by HomeSmart.
North Scottsdale's new-construction landscape, and who it suits
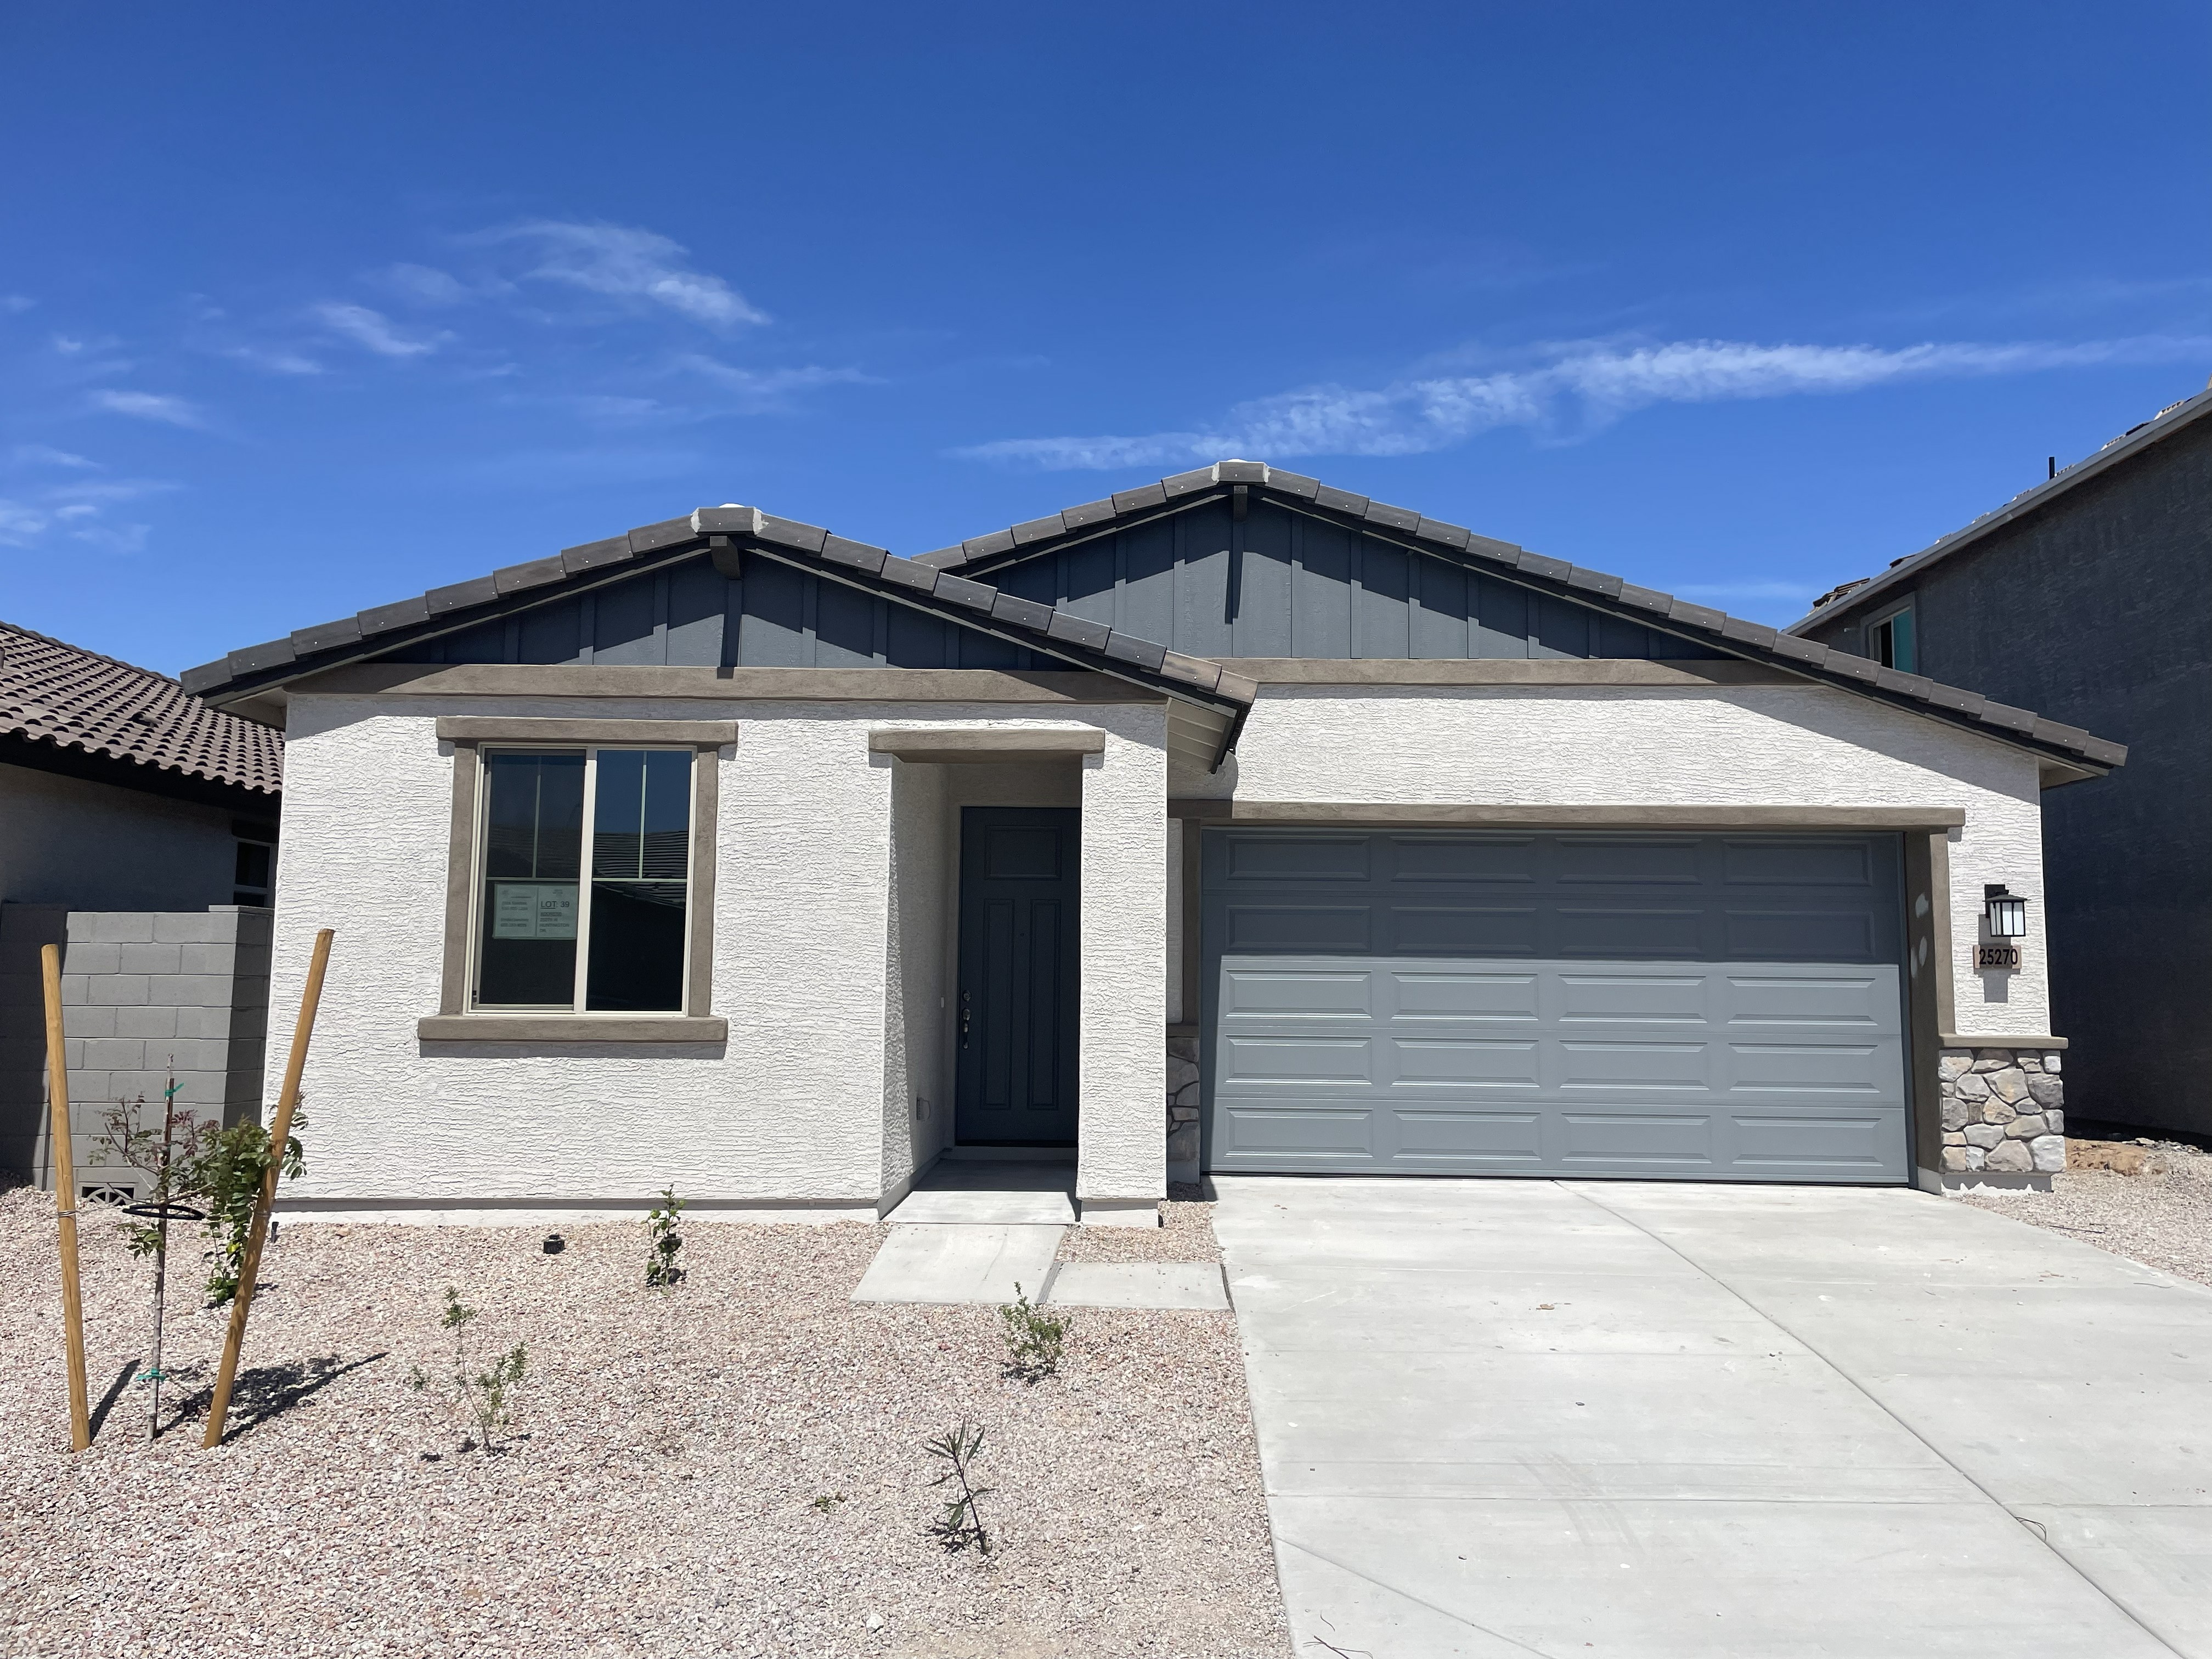
Scottsdale has very little land left, and most of what remains sits north of the 101 against the McDowell Mountains. That is where a North Scottsdale new build buyer will spend most of their time. The largest concentration is in 85255 around the Storyrock and Sereno Canyon master plans, where Toll Brothers and Shea Homes are both selling. Toll opened the final phase of Storyrock with single-level plans from 3,665 square feet. Further north in 85262, Toll's HighPoint collections and Camelot Homes' The Edge at Joy Ranch and Seven Desert Mountain carry the market toward Carefree and Desert Mountain.
The established names behave differently. DC Ranch is close to built out — Camelot sold all nine homes in The Legacy at DC Ranch, its newest neighborhood. Inside it, Silverleaf is now almost entirely custom: individual estates by builders such as Cullum, Salcito, and Sommer, plus the ICON at Silverleaf condominiums, where 24 of 72 units remained available at last report. Grayhawk and Windgate Ranch are finished master plans. A buyer who wants those addresses is shopping resale, and new construction nearby is the comparison rather than the alternative.
Who does a new build suit. Buyers who want a single-level plan with current energy code and a builder warranty. Buyers relocating with flexibility on timing, who can wait for a build slot and want to choose their own finishes. Buyers whose agent can turn a standing-inventory home into a negotiation, because a finished spec home is the one asset a builder is paying interest on every month it sits. And it suits buyers less well when the calendar is fixed or the budget has no room for the projects a builder leaves undone.
Here is the active field, using the ranges builders publish through Homes.com. The low end of each range is usually a base plan; the high end is a finished, optioned, often move-in-ready home on a premium lot.
| Community | Builder | Zip | Published range |
|---|---|---|---|
| Aria at Silverstone | K. Hovnanian | 85255 | $899,990 – $1,104,190 |
| Sereno Canyon, four collections | Toll Brothers | 85255 | $1,389,995 – $3,207,995 |
| HighPoint, Pinnacle and Summit | Toll Brothers | 85262 | $1,584,995 – $2,660,000 |
| The Reserves at Storyrock | Shea Homes | 85255 | $1,899,990 – $2,984,671 |
| Storyrock, Canyon and Overlook | Toll Brothers | 85255 | $1,965,995 – $3,670,000 |
| Preserve Ranch | David Weekley Homes | 85255 | $2,289,990 – $4,299,000 |
| Seven Desert Mountain, The Villas II | Camelot Homes | 85262 | $2,429,900 – $2,449,900 |
| The Edge at Joy Ranch | Camelot Homes | 85262 | $2,427,900 – $4,141,900 |
| Signature at Storyrock | Shea Homes | 85255 | $2,781,990 – $4,395,000 |
| Shadow Ridge | Camelot Homes | 85255 | From $2,939,900 |
| Silverleaf, DC Ranch, Windgate Ranch, Grayhawk | Custom builders or resale | 85255 | Resale medians from about $955,000 (Grayhawk) to about $4.7M (Silverleaf) |
Source: builder-published community ranges on Homes.com, as of 2026; ranges combine collections where a builder sells more than one in the same master plan. Resale medians from Redfin neighborhood data. Builder pricing changes weekly and includes inventory homes with options; confirm current price sheets with each sales office. Listing a community here is not an endorsement of any builder.
Before your first model-home visit, talk with us. We will register with the builder alongside you, so your representation is in place from the first conversation rather than added after it.
The builder contract: base price, upgrades, lot premiums, and incentives
The first thing to understand about buying new construction in Scottsdale is that there is no standard contract. A resale purchase here is written on the Arizona REALTORS® form, which both sides know line by line. A builder writes its own agreement, and it is drafted to protect the builder. Read it for the financing contingency, which may let the builder cancel if your loan fails without protecting your deposit. Read it for the completion date, which is usually an estimate the builder can extend. And read it for the earnest money: Arizona's Department of Real Estate advises buyers to check where the deposit is held, since on a new home it may go to the builder rather than sit in a neutral escrow.
The same department requires the builder to hand you the subdivision Public Report, and to get your signed receipt, before you sign. It is the least-read document in the transaction and one of the most useful. It covers water and utility providers, assessments, flood and drainage, and the association. Read it before the design appointment, not after.
Then the price, which arrives in four layers. The base price is the plan on a standard lot with standard specifications. The structural options — a casita, an extended great room, a third garage bay, a covered patio past the slab — are chosen early because they change the framing. The design studio follows, where flooring, cabinetry, counters, lighting, and plumbing fixtures are each priced with a margin built in. Finally the lot premium, charged for a view, a preserve edge, a cul-de-sac, or simply more land. On a North Scottsdale homesite with a mountain view, the premium alone can rival the cost of a kitchen.
The model you toured is not the base price. It is the base price plus every decision the builder hopes you will make.
Incentives are where new home negotiation in Scottsdale actually happens. In the NAHB/Wells Fargo Housing Market Index, as of 2026, 43% of builders reported cutting prices — the highest share of the 2020–2026 period — with the average cut holding at 6% for seven straight months, and 65% reported using sales incentives. Builder confidence fell to 29, its lowest reading since 2012. Six percent of a $1,950,000 home is $117,000. That is the scale of what is on the table, though rarely all as one line.
What is actually negotiable follows a pattern. On a to-be-built home, builders tend to hold the base price, because every closed sale becomes a comparable for the next one. Value moves instead through design-studio credits, closing-cost contributions, and rate buydowns — the last often tied to the builder's affiliated lender. On standing inventory the price itself becomes negotiable, and the incentive is usually larger. A lot premium can sometimes be reduced on a homesite that has sat. And a buydown needs reading closely: a temporary buydown lowers the payment for a year or two, while a permanent one lowers the rate for the life of the loan. They are often quoted in the same breath. They are not the same thing.
Rates make that distinction expensive. Freddie Mac's Primary Mortgage Market Survey put the 30-year fixed average at 7.18% in early November 2026. On a $1,692,000 loan, a one-point lower rate for the full term is worth about $1,121 a month in principal and interest. Compare an incentive in those terms — dollars of payment over the years you expect to own — and the right choice between a price cut, a credit, and a buydown usually becomes obvious.
Timelines, inspections, and warranties on a new build
A new build runs on two clocks. A to-be-built home moves from contract to structural selections, design studio, permit, foundation, framing, and finishes, and its closing date is a forecast measured in months. A standing-inventory or move-in-ready home closes on a normal mortgage timeline, with fewer choices and usually more room to negotiate. Many North Scottsdale buyers do best with a home partway through construction — late enough to know the date, early enough to influence the finishes.
Plan your rate protection around whichever clock you are on. A long build can outlast a standard rate lock, and an extended lock carries a cost. If the builder's incentive depends on its preferred lender, ask that lender and an outside lender for the same quote on the same day, with the incentive applied, before you decide.
Inspect a new home anyway. City inspections confirm code compliance; they do not represent you. An independent inspector at two moments covers most of the risk. The first is pre-drywall, when framing, plumbing, electrical, and window flashing are still visible. The second is before the final walkthrough, when the finished home can be tested and a punch list written while the builder's trades are still on site. Check the contract for inspection access rules first, since many builders require scheduling and proof of insurance. A third inspection, shortly before the first warranty year ends, catches what a season of Scottsdale heat has revealed.
Warranties come in two layers. The first is the builder's written limited warranty, often tiered — a short term for workmanship, a longer one for systems, and the longest for structure — with exclusions that matter, so read the actual document. The second is Arizona law. Contract claims against a builder generally must be brought within eight years of substantial completion under A.R.S. § 12-552. And before filing a construction-defect claim, a purchaser must send written notice by certified mail under A.R.S. § 12-1363, which gives the builder 60 days to respond and a right to repair. Keep every email, photo, and service ticket from the first day.
Interactive: the new-build budget calculator
Enter the builder's numbers line by line to see the all-in contract price, the loan it implies, and an estimated monthly payment. The defaults are an illustrative Storyrock-range scenario, not a quote: a $1,950,000 base, $150,000 in options, a $75,000 lot premium, a $60,000 incentive, 20% down, and Freddie Mac's current 7.18% average. Replace every one with the builder's price sheet and your lender's quote.
New-Build Budget Calculator
Slide from $800,000 to $5M, or type any base price above.
Enter a price reduction or design credit here. If the incentive is a rate buydown instead, leave this at zero and enter the bought-down rate below.
Optional. Enter zero if you are not selling.
Your all-in price
| Base, options, and lot premium | — |
| Less builder incentive | — |
| All-in contract price | — |
| Down payment | — |
| Loan amount | — |
Estimated monthly cost
| Principal and interest | — |
| Property tax and insurance | — |
| Association dues | — |
| Estimated monthly total | — |
| Cash needed: down payment plus post-closing projects | — |
If you sell your current home with us
| Our listing fee — 1%, $5,500 minimum | — |
| Listing fee at 3% | — |
| Kept toward your down payment | — |
Read the default scenario as a shape rather than a forecast. A $1,950,000 base becomes $2,175,000 before the incentive and $2,115,000 after it. At 20% down that is $423,000 in cash and a $1,692,000 loan, about $11,462 a month in principal and interest at 7.18%, and about $12,546 a month once an estimated $10,000 a year in tax and insurance and $250 in dues are added. The cash line is the one buyers underestimate: $423,000 down plus $60,000 for the yard and window coverings is $483,000 before a single closing cost.
The bottom block matters for the many buyers here who are also sellers. Selling a $550,000 home at our 1% fee costs $5,500 rather than $16,500 at 3%, which leaves $11,000 more for the down payment, the rate lock, or the backyard. At $1,100,000 the difference is $22,000. Our North Scottsdale and Paradise Valley luxury breakdown runs the same arithmetic above $2M.
Send us the builder's price sheet and the incentive offer. We will rebuild the all-in number, compare the incentive against a price cut and a buydown, and show you which lines are worth negotiating.
Why a Scottsdale buyer agent on a new build is worth having
The people in the sales office are often excellent, and they are paid by the builder to sell the builder's homes. That is a fair arrangement. It is also why a buyer benefits from someone whose only client is the buyer. The builder has a contract it wrote, a lender it prefers, a design studio with margins, and a lot list it would like to clear. You have one transaction and no one else reading it on your side.
Timing is the part buyers miss. Arizona's Department of Real Estate states that a consumer who visits a new home development without a representative may return with one, but the representative may not receive a commission. Builders generally require the buyer's agent to be at the first visit, or to register the buyer in advance, to be eligible for the builder's compensation. Arizona's standard buyer-broker agreement addresses this directly. So the model-home walk-through on a Saturday afternoon, the one that felt like browsing, can decide the economics of your representation.
On new construction, representation is decided at the front door of the model home, not at the closing table.
What the work looks like in practice. We compare the builder's effective price against resale in the same zip — with 85255 resale running about $521 a square foot on Redfin's figures, Storyrock's Canyon Collection, published from $1,965,995 with plans from 3,665 square feet, starts near $536 a foot — close enough that the options and the lot premium decide the value. We read the contract for the financing contingency, the completion-date language, and the deposit terms. We price the incentive three ways. We push for the concessions builders actually grant: closing-cost help, design-studio credit, a lot-premium reduction on a homesite that has waited, or a better price on a spec home nearing completion. We schedule the independent inspections and keep the record that A.R.S. § 12-1363 will want if anything goes wrong.
For our part: 22 years across the Phoenix metro, more than 3,000 homes sold, over $900M in closed transactions, and more than 500 five-star reviews. We are brokered by HomeSmart, and one licensed agent negotiates and writes every contract. Our buyer services set out what representation includes. If the purchase depends on selling first, our seller services cover that side at a 1% listing fee with a $5,500 minimum and no upfront costs.
How buyer's agent compensation works on a new build
Since the practice changes that took effect in August 2024, you will sign a written agreement with your agent before touring, and it states what the agent will be paid. Compensation remains fully negotiable. Any seller — a builder included — may choose to offer compensation to a buyer's agent, and none is required to.
In practice, many builders publish their own broker-cooperation terms, often conditioned on registration at the first visit. When a builder offers compensation, it is typically credited against what your agreement provides. When it offers less or nothing, your agreement governs the difference, and it can be raised in the negotiation alongside closing costs and design credits. We lay this out in writing before you tour, so the numbers are settled before anyone is choosing countertops.
Questions buyers ask about new construction in North Scottsdale
Can I negotiate the price on a new home in Scottsdale
Often, though not always on the base price. Builders tend to protect the base on to-be-built homes and give value through design credits, closing-cost help, and rate buydowns. Standing inventory is where price itself moves most. As of 2026, the NAHB reports 43% of builders cutting prices, with an average cut of 6%, so a well-prepared offer on the right home has room to work.
Do I need my agent at the first model-home visit
Yes, if you want representation the builder will compensate. Arizona's Department of Real Estate notes that a buyer who visits alone may later return with an agent, but that agent may not be paid by the builder. Bring us to the first visit, or call before you go so we can register you in advance.
Should I get an inspection on a brand-new home
Yes. City inspections check code compliance; an independent inspector works for you. The two most valuable moments are pre-drywall, while framing and systems are visible, and before the final walkthrough. A third inspection near the end of the first warranty year catches what a summer has exposed.
Do I have to use the builder's lender
Usually not, but an incentive may depend on it. Get a same-day quote from the builder's lender and an outside lender with the incentive applied, then compare total cost over the years you expect to keep the loan. A larger credit with a higher rate can cost more than it saves.
What if I need to sell my current home first
Plan the two transactions together. A build-to-order timeline can help, since the sale can be timed to the estimated completion. We can list your current home at 1% of the sale price with a $5,500 minimum and no upfront costs. At $550,000 that is $5,500 rather than $16,500 at 3%, which leaves $11,000 more for the new home.
Full-service. Honest pricing.
The builder has a team. So should you.
A free buyer consultation for North Scottsdale new construction: which communities fit your budget and timeline, how to register before your first visit, what the incentive is really worth, and how to fund it — including what you keep if you sell your current home at our 1% listing fee.
Get Your Free ConsultationSources and further reading: NAHB/Wells Fargo Housing Market Index — builder price cuts and incentives · Freddie Mac — Primary Mortgage Market Survey · National Association of REALTORS® — what the settlement means for homebuyers · Arizona Department of Real Estate — new home construction · Arizona Department of Real Estate — property buyer's checklist · Arizona Legislature — A.R.S. § 12-1363 · Homes.com — new home communities in Scottsdale · Toll Brothers — Storyrock, Scottsdale · DC Ranch — construction projects · Redfin — 85255 · Redfin — Silverleaf · Redfin — Grayhawk.