November 11, 2026
Buying a Condo in Scottsdale: HOA Due Diligence and Carrying Costs
Buying a condo in Scottsdale means vetting the HOA. Learn which documents to read, how lenders review the building, and your true monthly carrying cost.
12 Min Read
Key Takeaways
- In Scottsdale, the median condo sold for $369,900 and the median townhouse for $568,715, against $1,274,273 for a single-family home.
- The HOA is half of what you are buying. Read its budget, reserves, minutes, and lawsuit summary before your inspection period ends.
- Lenders review the building as well as the borrower. Thin reserves, heavy delinquencies, or pending litigation can stall a loan.
- Rental rights live in the recorded declaration, and Scottsdale requires a city license for stays under 30 days.
- Run the full monthly number (mortgage, HOA dues, taxes, and insurance) before you write an offer.
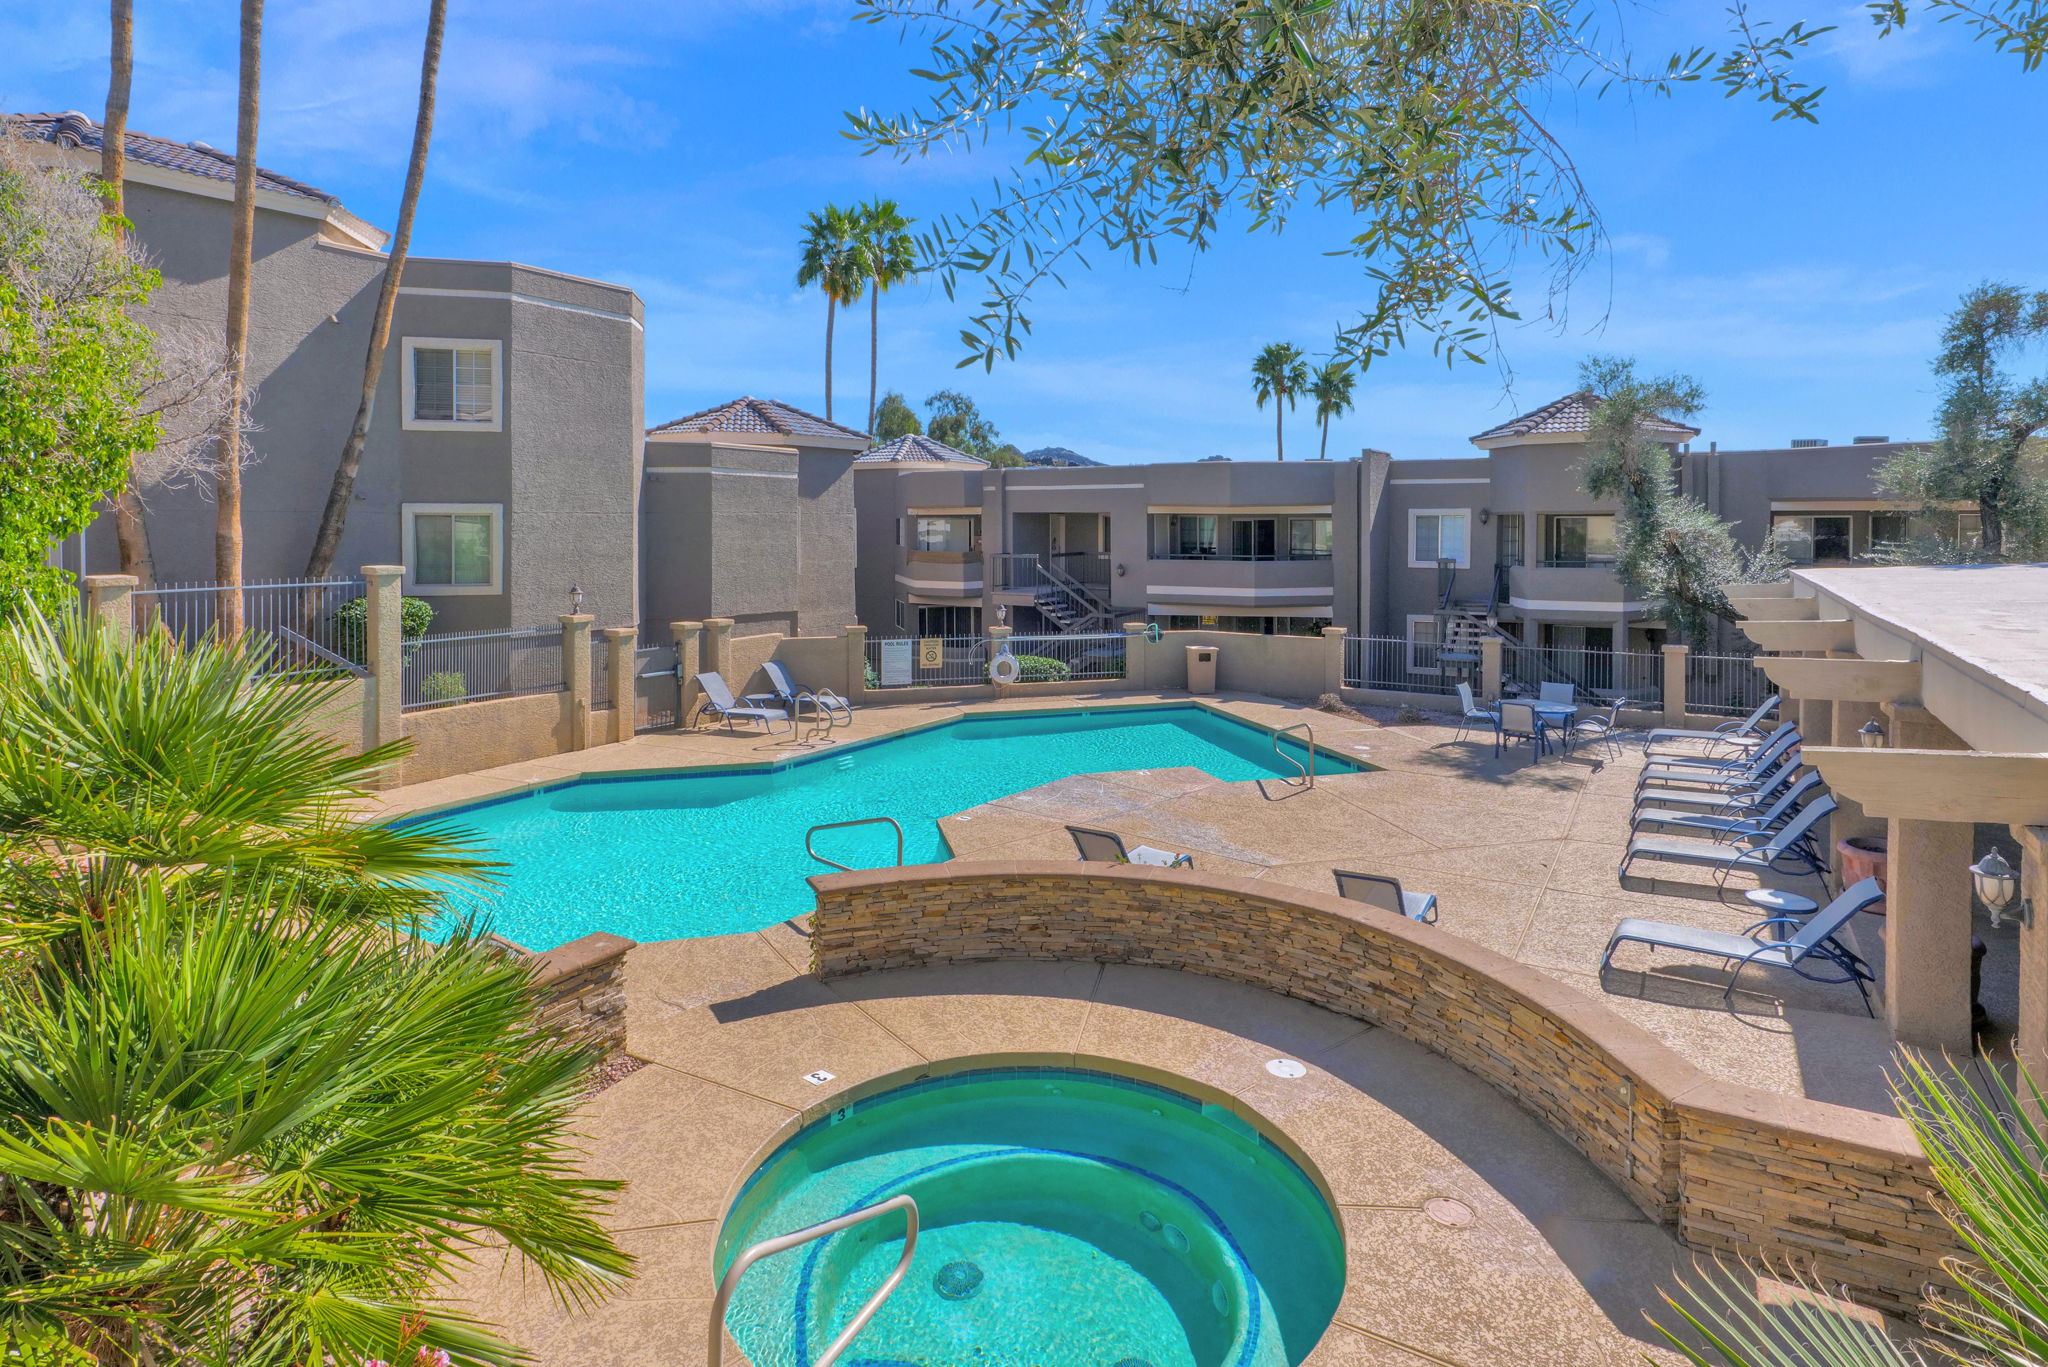
Buying a condo in Scottsdale is a different exercise from buying a house. You are purchasing a unit, a share of a building, and a seat in an association whose budget, rules, and legal history will shape your costs for as long as you own. The lock-and-leave appeal is real. So is the homework. This guide walks a Scottsdale condo or townhome buyer through the HOA documents that matter, the lending wrinkles specific to attached homes, the true monthly carrying cost, and the rental rules an investor needs to confirm before the contract goes firm.
Why buyers choose Scottsdale condos and townhomes
Most attached-home buyers we meet fall into three groups. Seasonal residents want a place they can close up in May and reopen in October without worrying about a yard, a roof, or a pool pump. Downsizers want one level, less maintenance, and a shorter walk to dinner. Investors want a unit that rents well and holds value in a city with steady visitor demand.
Price is the other draw. In Scottsdale, the median sale price across all home types was $909K over the three months ending October 2026, up 9.0% from a year earlier, according to Redfin. Broken out by property type, Redfin's Scottsdale city data puts the median single-family sale at $1,274,273, the median townhouse at $568,715, and the median condo at $369,900. That is roughly $904,000 between the typical condo and the typical house.
The lower price buys convenience, not freedom from cost. Dues replace some of what a homeowner would spend on exterior upkeep, landscaping, and amenities, and the association, not you, decides when the roof gets replaced and how it gets paid for. A lock and leave Scottsdale buyer is trading control for simplicity. That trade works well when the association is run well, and poorly when it is not.
Location shapes the choice too. Old Town Scottsdale offers walkable lofts and mid-rise condos near restaurants and galleries. Gainey Ranch and McCormick Ranch offer gated townhome enclaves around golf, lakes, and greenbelts. Scottsdale Ranch adds lakeside villas and paths a little farther east. Each pocket has a different mix of building ages, dues, and rental rules, which is why the next section matters more than the floor plan.
Condo, townhome, or single-family: the ownership tradeoffs
The table below compares what you own, what you maintain, and what the association controls in each format. Exact terms vary by community, so treat it as a starting framework and confirm every line against the declaration of the specific property.
| Factor | Condo | Townhome | Single-family |
|---|---|---|---|
| Scottsdale median sale price | $369,900 | $568,715 | $1,274,273 |
| What you own | The unit interior plus a share of common elements | Usually the structure and lot, inside an HOA | House and lot outright |
| Roof and exterior | Association, funded by dues and reserves | Varies; often shared or association-handled | Owner |
| Insurance | HO-6 policy plus the master policy and its deductible | Often HO-3; check what the HOA covers | HO-3 policy |
| Monthly dues | Highest; may include water, trash, amenities | Moderate | None to modest |
| Rental flexibility | Set by the declaration; often limited | Set by the declaration | Broadest, subject to any HOA |
| Loan review | Borrower and building both reviewed | Lighter project review in most cases | Borrower and property only |
| Lock-and-leave ease | Highest | High | Lowest |
Source: median sale prices from Redfin's Scottsdale city guide, updated October 2026. Ownership and maintenance rows are general patterns; the recorded declaration of each community controls.
Buyer consultation
Have a building in mind? We will read the HOA file with you.
Send us the address or the listing. We will tell you which documents to request, what to look for in the reserves and minutes, and how attached-home financing could affect your offer.
Schedule ConsultationHOA due diligence for buying a condo in Scottsdale
Arizona law gives you a real head start. Under A.R.S. 33-1260, a condominium seller must deliver a disclosure package, and in communities of 50 or more units the association prepares it within 10 days of the seller's written notice. The package includes the bylaws and rules, the recorded declaration, minutes from the last three open board meetings, the operating budget, the latest audit or financial review, the most recent reserve study if one exists, a summary of pending lawsuits, insurance certificates with coverage limits and deductibles, and any approved or pending special assessments. The same statute caps the association's aggregate charge for preparing it at $400, with limited rush and update fees. Who pays which transfer charge is negotiable; our guide to Scottsdale HOA transfer fees covers how those costs usually split.
Most buyers skim that stack. We read it in a set order.
- The budget. Look at how much of annual assessment income goes to replacement reserves. Fannie Mae's full project review expects that allocation to be at least 10% of the budget.
- The reserve study. Compare the money actually in reserve with what the study says the association needs for roofs, paving, pools, and elevators. A large gap is the most common source of future special assessments.
- Delinquencies. The same Fannie Mae review limits projects to no more than 15% of units that are 60 days or more past due on dues. High delinquency means the paying owners carry the rest.
- The minutes. Three meetings of minutes tell you what the board is worried about: leaks, deferred repairs, insurance renewals, or a dispute with a contractor.
- Litigation. Under Fannie Mae's ineligible-project rules, pending litigation tied to safety, structural soundness, habitability, or functional use makes a project ineligible for sale to Fannie Mae.
- Rental terms. Find the leasing section of the declaration and any rental time-period restrictions. More on this below.
Reading the reserve picture
A well-run association with a modest budget is better than a beautiful building with an empty reserve account. Ask the management company three questions in writing: when the last reserve study was completed, what percentage funded the reserves are today, and whether any special assessment is under discussion. The statute already requires disclosure of special assessments that are approved but not yet levied, or submitted for an owner vote in the prior four months. What it cannot tell you is what the board has been avoiding. The minutes usually can.
The HOA is half of what you are buying. Read its books with the same care you give the kitchen.
Ownership concentration
Arizona's disclosure statute also asks whether any corporation or LLC owns and leases 35% or more of the units. A building dominated by one investor can vote as a bloc, and heavy rental concentration can affect both lending and the feel of the community. If the answer is yes, slow down and ask how board seats are filled.
Carrying costs and lending nuances on attached homes
The mortgage payment is only part of the monthly picture. Every Scottsdale buyer agent condo conversation we have eventually lands on four lines: principal and interest, HOA dues, property taxes, and insurance. Dues are the line that surprises people, because they can rise each year with the budget and occasionally jump with a special assessment.
Insurance has two layers
In a condo, the association's master policy usually covers the building structure, and you buy an HO-6 policy for interior finishes, personal property, and liability. The gap that catches buyers is the master policy deductible. If the HOA's deductible is high and a loss originates in your unit, the association may look to you for part of it. Arizona's resale disclosure must include insurance certificates showing coverage limits and deductibles, so you can price that exposure with your insurance agent before you close.
The lender reviews the building
On a conventional loan for a condo, the lender typically confirms that the project meets agency standards as well as reviewing your credit and income. Fannie Mae's rules treat several project traits as disqualifying, including buildings that are primarily transient or run hotel-type services such as daily rentals and front-desk registration, projects in need of critical repairs, and projects where nonresidential or commercial space exceeds 35%. A unit in a building that fails those tests is often called non-warrantable. It can still be financed, usually through portfolio or specialty loans with larger down payments and different pricing.
This matters most in mixed-use towers in Old Town Scottsdale and in older resort-style communities. Ask your lender to review the project before you are deep into escrow, and keep the financing contingency intact until the lender confirms the building qualifies. Townhomes structured as planned-community lots usually face a lighter review, which is one reason some buyers prefer them.
Interactive: Scottsdale condo carrying-cost calculator
Enter the list price, your down payment, a rate quote from your lender, the HOA dues from the disclosure package, the annual tax bill for the parcel, and an HO-6 insurance quote. The defaults start at Redfin's Scottsdale median condo price; every other default is an illustrative assumption you should replace with real figures.
Condo carrying-cost calculator
Assumes a 30-year fixed loan. Rate, dues, tax, and insurance defaults are illustrative only.
| Loan amount | $295,920 |
| Principal and interest | $1,822 |
| HOA dues | $350 |
| Property tax | $150 |
| HO-6 insurance | $50 |
| Estimated monthly carrying cost | $2,372 |
| Share of the payment that is not the mortgage |
If you later sell this unit with MyAgentForLess, the listing fee at this price would be $5,500 (the $5,500 minimum applies below $550,000).
At the defaults, a $369,900 condo with 20% down carries about $2,372 a month, and roughly 23% of that is dues, taxes, and insurance rather than the loan. Change the HOA line to the real figure from the disclosure package and watch how quickly the total moves.
Run the real numbers
Turn a list price into a monthly number you can trust.
We pull the actual dues, tax history, and special assessment status for the units you are considering, so your offer rests on facts rather than estimates.
Schedule ConsultationInvestment angle: what a Scottsdale townhome buyer should know about rental rules
If rental income is part of the plan, the declaration decides the plan. Arizona's Condominium Act provides that a unit owner may rent the unit unless the declaration prohibits it, and must follow the declaration's rental time-period restrictions. The Planned Communities Act contains a parallel rule for townhome and single-family lots in A.R.S. 33-1806.01, which also limits the tenant-information fee an association can charge to $25 per new tenancy. In practice, many Scottsdale communities set minimum lease terms of 30 days or longer, and some have amended their declarations to restrict short stays. Read the current recorded version, not a summary in the listing.
The city adds its own layer. The City of Scottsdale requires an annual short-term rental license for each property rented for less than 30 days, at $250 per property per year. Operators also need an Arizona transaction privilege tax license, liability coverage of at least $500,000, and written notice to neighbors within 30 days of licensing. In a condo building, that notice goes to every unit on the same floor.
Short-term rental use can also affect financing for the next buyer. A building where daily or weekly stays become the norm can drift toward the transient profile that Fannie Mae treats as ineligible. That can shrink your eventual buyer pool. Many investors in Gainey Ranch and McCormick Ranch therefore favor seasonal furnished leases of a month or more, which fit most declarations and match the winter demand Scottsdale is known for.
Where the submarkets sit
Redfin's all-home-type medians give a sense of each area's price band, although they blend condos, townhomes, and houses. Over the three months ending October 2026, Old Town's median was $599K, up 7.1%, with homes taking about 81 days to sell. Gainey Ranch posted a $1.3M median, up 9.5%, and McCormick Ranch posted $915K, up 6.4%, though its typical days on market stretched to 95. Redfin's most recent reading for Scottsdale Ranch showed an $850K median, up 1.8%. Citywide, homes sold at about 96.4% of list price. That gap between asking and closing is where a well-prepared buyer negotiates. For the wider metro picture, see our Phoenix real estate market outlook.
How buyer's agent compensation works after the NAR settlement
Since August 17, 2024, agents who use the MLS must sign a written agreement with a buyer before touring a home. That agreement states the agent's compensation in objective terms, such as a flat fee or a percentage, and compensation remains fully negotiable. A seller may choose to offer compensation toward the buyer's agent or a concession you can apply to it. That offer is the seller's choice, never a requirement, and it can be part of your negotiation like any other term.
We walk every buyer through the agreement line by line before the first showing, so there are no surprises at the closing table. Our buyer representation is led by the same senior agent who negotiates every contract, backed by 22 years in the Phoenix metro, 3,000+ homes sold, $900M+ in closed transactions, and 500+ five-star reviews. If you later sell the unit with us, our listing fee is 1% of the sale price with a $5,500 minimum, and there are no upfront costs. 1% Listing, No Gimmicks.
Frequently asked questions
What should I look for in a Scottsdale condo HOA's financials?
Start with the share of the budget set aside for replacement reserves; Fannie Mae's review standard is at least 10%. Then compare actual reserve balances with the reserve study, check delinquency levels, and read the last three meetings of minutes for deferred repairs or talk of a special assessment.
Can I rent out a condo or townhome in Scottsdale?
Usually, unless the recorded declaration prohibits it or sets minimum lease terms. For stays under 30 days, the City of Scottsdale also requires an annual license, an Arizona transaction privilege tax license, and at least $500,000 in liability coverage.
Why would a lender decline a condo I can afford?
Because the building did not pass project review. Pending litigation over safety or habitability, critical repairs, hotel-style operations, or more than 35% commercial space can make a project ineligible for conventional financing. Specialty loans may still be available on different terms.
Do I have to pay my buyer's agent out of pocket?
It depends on your written buyer agreement and on what the seller chooses to offer. Compensation is negotiable, and a seller may offer to cover some or all of it, but nothing requires them to. We explain every option before you tour.
Free buyer consultation
Buying a Scottsdale condo or townhome? Start with the right questions.
Whether you want a lock-and-leave base in Old Town Scottsdale or a rental in Scottsdale Ranch, we will review the HOA documents, model your carrying costs, and negotiate the contract. Full-service. Honest pricing.
Get Your Free ConsultationSources and further reading: Redfin: Scottsdale housing market · Redfin: Scottsdale prices by property type · Redfin: Old Town market · Redfin: Gainey Ranch market · Redfin: McCormick Ranch market · Redfin: Scottsdale Ranch market · A.R.S. § 33-1260: condo resale disclosure and fees · A.R.S. § 33-1260.01: condo rental rights · A.R.S. § 33-1806.01: planned-community rental rights · Fannie Mae Selling Guide: condo project review · Fannie Mae Selling Guide: ineligible projects · City of Scottsdale: short-term rental requirements · National Association of REALTORS®: what the settlement means for homebuyers.